

Multifamily Property Tax Reassessment: How One Expense Changes NOI, Value, and Debt
A seller's property tax expense may be accurate historically but wrong for the buyer. Here's how to model reassessment risk and its effect on acquisition pricing, NOI, and financing.
Market and statutory references reviewed October 27, 2026. The acquisition examples are illustrative.
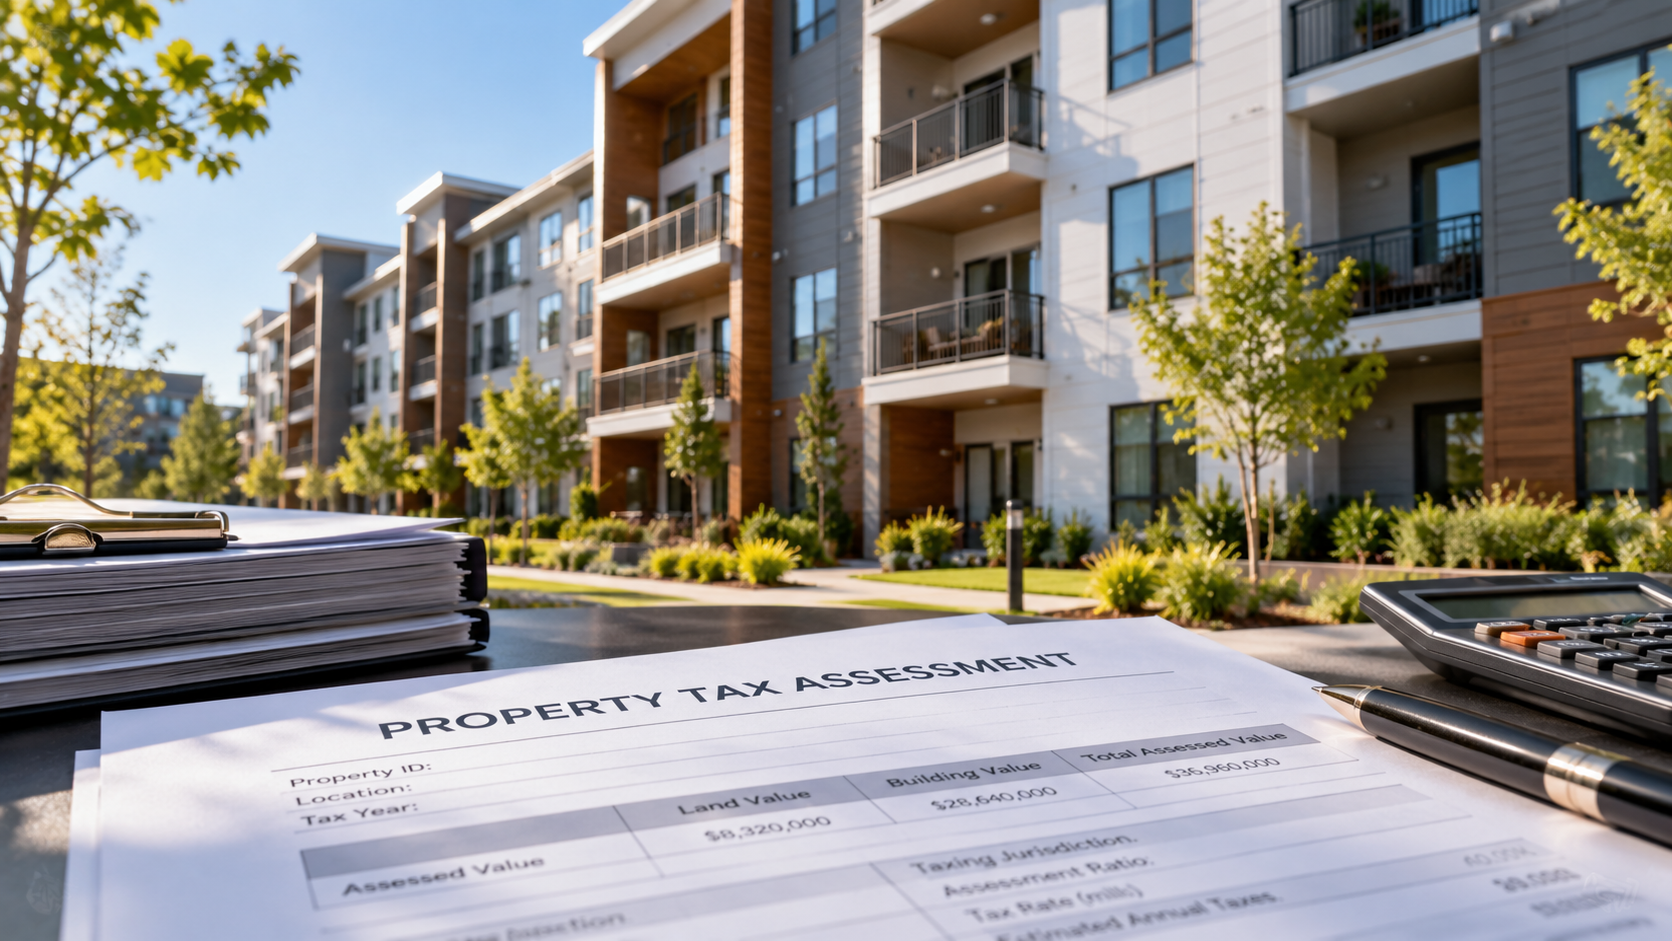
A multifamily seller reports $480,000 in annual property taxes.
The buyer carries that expense into the acquisition model. After reviewing the property's assessment history and local tax rules, the buyer estimates that the full-year property-tax obligation under new ownership could reach $820,000.
That's a $340,000 difference in annual operating expenses, before a single apartment is renovated or any operational improvement takes effect.
At a hypothetical 6.00% capitalization rate, a permanent $340,000 reduction in net operating income (NOI) represents approximately $5.67 million in indicated property value, all else equal.
Same property. Same revenue. A substantially different investment.
The seller's financial statements might be accurate. The buyer's underwriting can still be wrong.
When we underwrite a multifamily acquisition, property taxes are one expense I do not want to accept at face value. A property's current tax bill reflects its historical assessment, local rules, and circumstances that may change under new ownership or at a future reappraisal.
The consequences extend beyond NOI. A higher tax obligation can reduce debt-service coverage, lower supported loan proceeds, increase the equity required to close, and ultimately change what we should be willing to pay.
The question is not simply whether property taxes will increase. It is what the next owner should reasonably expect to pay, when that obligation begins, and whether the acquisition still works after accounting for it.
TL;DR
A multifamily property's historical tax expense is not necessarily its future tax expense.
Depending on the jurisdiction, ownership changes, scheduled reappraisals, assessment limitations, and improvements can affect taxable values. A sale does not automatically reset every property's assessment to its purchase price.
For our hypothetical 240-unit acquisition, increasing annual property taxes from $480,000 to $820,000 reduces NOI by $340,000. At an illustrative 6.00% cap rate, that is approximately $5.67 million in indicated value.
Under the specified financing assumptions, the same change reduces supported loan proceeds by approximately $1.05 million, increasing required acquisition equity.
I evaluate property taxes using six steps: VERIFY → CLASSIFY → REVALUE → TIME → STRESS → MONITOR.
The objective is to establish a supportable forecast and decide whether the acquisition still makes sense after accounting for its forward tax obligations.
Why the Seller's Property Tax Expense Can Be Misleading
A trailing 12-month financial statement tells us what a property recorded historically. It does not necessarily tell us what the next owner will pay.
The seller's taxes may reflect an assessment established years earlier, an applicable valuation limitation, a particular ownership situation, or an exemption. A property may have appreciated substantially while its taxable assessed value increased more slowly.
We also need to distinguish annual tax liability from the expense recognized in the T12. Accrual methods, payment timing, refunds, and accounting classifications can cause those amounts to differ.
I separate three measures during underwriting.
| Tax measure | What it represents | Underwriting purpose |
|---|---|---|
| Seller historical taxes | Taxes recorded in seller financials | Reconcile historical NOI |
| Current tax obligation | Taxes based on the current assessment and rates | Verify existing liability |
| Buyer forward taxes | Expected expense under the buyer's ownership | Underwrite NOI, debt, and returns |
These numbers can be identical. They can also be materially different. The mistake is assuming they are identical without investigating.
Understanding how property taxes are calculated
Fair market or appraised value is the property's value under the applicable assessment methodology.
Assessed value reflects the jurisdiction's assessment ratio or other valuation rules.
Taxable value may differ after applying exemptions, limitations, and adjustments.
Tax rate or millage determines the levy applied to the taxable base.
Some tax bills include assessments or charges that do not follow ordinary ad valorem valuation rules. The complete bill must therefore be reviewed.
For example, consider a hypothetical Georgia apartment property with a $40 million fair-market valuation.
| Component | Illustrative amount |
|---|---|
| Fair market value | $40,000,000 |
| Georgia assessment ratio | 40% |
| Assessed value | $16,000,000 |
| Assumed combined tax rate | 30 mills |
| Estimated annual ad valorem taxes | $480,000 |
Georgia generally assesses property at 40% of fair market value unless another provision applies. The 30-mill rate is hypothetical, not a quotation for a particular county.
Sources: Georgia Department of Revenue, Property Tax Valuation and Property Tax Millage Rates .
A Sale Does Not Trigger the Same Reassessment Everywhere
One statement comes up frequently in multifamily acquisitions: "When we buy the property, the county will reassess it at our purchase price."
That may identify a legitimate risk, but it is not a universal rule. Different states use different valuation schedules, assessment ratios, ownership-change provisions, and limitations.
Georgia: Annual fair-market-value assessments
Georgia generally assesses real property at 40% of fair market value. The annual valuation process is tied to January 1, but Georgia does not operate under one uniform statewide six- or eight-year countywide reappraisal cycle.
A sale may provide relevant valuation evidence. It does not automatically establish that every apartment property will be assessed dollar for dollar at the closing price.
For Georgia acquisitions, I want the current county fair-market value, assessment history, applicable millage, recent comparable transactions, and any outstanding assessment dispute.
Source: Georgia Department of Revenue .
North Carolina: The reappraisal cycle matters
North Carolina generally requires counties to reappraise real property at least every eight years. Counties may choose more frequent cycles or be required to accelerate a reappraisal under specified conditions.
The next countywide reappraisal can materially affect an acquisition's projected tax obligation. A property purchased just before that event may have a different forward-tax outlook from one purchased shortly after it.
A higher appraised value should not automatically be converted into an identical percentage increase in taxes. Applicable rates and levy changes must also be considered.
Source: North Carolina General Statute 105-286 .
South Carolina: Assessment ratios and transfer-related relief
South Carolina generally applies a 6% assessment ratio to commercial and rental investment real property. A qualifying assessable transfer of interest can affect the property's valuation.
Section 12-37-3135 provides a potential partial exemption for certain qualifying transfers of property subject to the 6% assessment ratio.
Where eligible, the provision can allow an exemption equal to 25% of the assessable-transfer fair-market value, subject to the statutory current-value floor and eligibility requirements.
The resulting value for exemption purposes cannot fall below the property's defined current fair-market value. Where the applicable conditions are not met, the benefit may be reduced or unavailable.
The property generally must have been subject to tax at the 6% assessment ratio before the transfer and remain in that classification. The required notification must also be provided to the county assessor before January 31 for the initial qualifying tax year.
This is not an automatic 25% reduction in the property-tax bill. The benefit depends on the statutory conditions and the valuation used by the assessor.
I would obtain county confirmation or qualified property-tax advice before crediting projected NOI with any exemption.
Source: South Carolina Code, Sections 12-37-3135 and 12-37-3140 .
Ohio: Reappraisals, updates, and effective rates
Ohio generally requires a full property reappraisal every six years, with a valuation update in the third year. The Ohio Department of Taxation released an updated county schedule covering 2026 through 2031.
Real property is generally assessed at 35% of its appraised value. Effective rates, local levies, and applicable adjustments influence the final tax bill.
Recent property-tax law changes make verification of the specific taxing district especially important. For an Ohio acquisition, I would verify the county's actual reappraisal year and current effective rates before forecasting the next ownership period.
Sources: Ohio Department of Taxation and January 2026 Reappraisal Schedule Announcement .
Three additional markets worth understanding
| State | Relevant distinction | Underwriting consideration |
|---|---|---|
| California | Qualifying ownership changes generally establish a new Proposition 13 base-year value, subject to exclusions. | Review ownership-change treatment, fair-market value, and supplemental bills. |
| Florida | Section 193.1555 generally covers residential property with 10 or more units and other eligible nonresidential property. It includes a 10% annual assessment limitation for non-school levies and generally requires reassessment at just value following qualifying changes of ownership or control. | Verify classification, valuation date, school versus non-school levies, and ownership-change treatment. |
| Texas | The temporary non-homestead circuit-breaker limitation applies only to qualifying properties. The 2026 value threshold is $5.32 million, with expiration scheduled after 2026 unless extended. | Do not assume large apartment communities qualify for the limitation. |
Sources: California Board of Equalization , Florida Statutes, Section 193.1555 , and Texas Comptroller .
Property-tax forecasting is a local valuation and legal question before it becomes a spreadsheet assumption.
The MSA Property Tax Underwriting Framework
I use six steps to evaluate property-tax exposure in a multifamily acquisition.
1. VERIFY: Establish the existing obligation
Start with the parcel, not the T12. Obtain the last three years of tax bills, current assessment notices, parcel identification numbers, assessor records, and applicable taxing-district information.
Reconcile the tax history against the seller's operating statements and general ledger. Understand whether the expense represents accruals, actual payments, refunds, or adjustments relating to earlier years.
2. CLASSIFY: Determine which rules apply
Identify the property's classification, assessment ratios, limitations, exemptions, credits, and special assessments. Determine whether any seller-specific benefits survive the transaction.
3. REVALUE: Establish the buyer's supportable estimate
Evaluate the ownership-change rules, valuation methodology, next reappraisal date, and relevant market evidence.
Where appropriate, consider purchase consideration, comparable transactions, and supportable income or appraisal evidence. The result should be a reasonable tax estimate with a documented range of outcomes.
4. TIME: Model when the change affects the property
The closing date, valuation date, tax year, accounting expense, billing date, and payment date can differ.
Separate recurring tax expense from closing prorations, seller credits, supplemental bills, and lender escrow funding.
5. STRESS: Measure the investment consequences
Test the effect of a higher or lower obligation on NOI, valuation, debt coverage, loan proceeds, required equity, cash flow, and projected returns.
Do not replace a known reassessment risk with an unsupported annual growth percentage.
6. MONITOR: Update after closing
Track valuation notices, tax bills, millage, reassessment schedules, improvements, and appeal deadlines.
Potential appeal savings should be evaluated separately until sufficiently supported.
Worked Example: How a $340,000 Tax Increase Changes a 240-Unit Acquisition
HYPOTHETICAL CASE STUDY · NOT AN XSITE TRANSACTIONConsider a hypothetical 240-unit apartment community offered for $36 million.
The seller reports $2.75 million in annual NOI, including $480,000 in property taxes. Our buyer estimates a full-year forward tax obligation of $820,000.
First, where does the $820,000 tax estimate come from?
In an actual acquisition, we would build the estimate from assessor records, parcel classification, applicable rates, transfer rules, and the expected taxable valuation. We would document the evidence supporting each input.
To make the financial mechanics reproducible, assume this hypothetical property is in an unnamed taxing jurisdiction using the following simplified taxable-value calculation.
This is not a Georgia tax calculation and does not describe the law or tax rate of any particular county.
| Illustrative tax calculation | Seller historical | Buyer forecast |
|---|---|---|
| Taxable valuation basis | Approx. $21.07M | $36.00M |
| Assumed combined effective rate | 2.2778% | 2.2778% |
| Illustrative annual taxes | Approx. $480K | Approx. $820K |
The simplified bridge assumes the seller's taxable valuation is approximately $21.07 million, while the buyer estimates a forward taxable basis of $36 million.
The effective rate is held constant at an illustrative 2.2778% solely to isolate the valuation change. An actual underwriting model would separately estimate applicable millage changes, exemptions, special assessments, and other charges.
Under these assumptions, the calculation produces approximately $480,000 and $820,000 in annual taxes, respectively.
The buyer's illustrative taxable basis happens to equal the $36 million acquisition price. That is an assumption, not a legal rule. An actual assessor may determine a different taxable value, and the tax-rate structure may be considerably more complex.
This bridge demonstrates the calculation behind the hypothetical example. It does not establish that the increase would occur for a specific property.
Step 1: Reconcile the tax expense to NOI
| Operating measure | Seller financials | Buyer full-year estimate |
|---|---|---|
| NOI before property taxes | $3,230,000 | $3,230,000 |
| Property taxes | ($480,000) | ($820,000) |
| NOI after taxes | $2,750,000 | $2,410,000 |
The adjustment reduces NOI by $340,000, approximately 12.4% of the seller-reported amount.
To offset the tax increase, the property would need approximately $118 in additional monthly NOI per unit across all 240 units.
That is not the same as charging $118 more in gross monthly rent. Vacancy, concessions, bad debt, and other operating expenses could require a larger increase in collected revenue.
Step 2: Recalculate the acquisition cap rate
The difference is approximately 94 basis points.
The property has not changed. Our understanding of its forward NOI has.
Step 3: Understand the valuation impact
A permanent $340,000 annual NOI difference represents approximately $5.67 million in indicated value at a 6.00% capitalization rate, holding other assumptions constant.
That is a sensitivity, not a prediction that the seller must reduce the price by $5.67 million.
The actual impact depends on timing, recurring tax expectations, market capitalization rates, and the tax assumptions embedded in comparable transactions.
Once higher recurring taxes reduce normalized NOI, they should not be deducted again from capitalized value as a separate expense without an independently justified reason.
Step 4: Determine the effect on debt proceeds
Assume the following hypothetical lender requirements.
| Financing assumption | Value |
|---|---|
| Maximum LTV | 70% |
| Minimum DSCR | 1.25x |
| Fixed interest rate | 7.00% |
| Amortization | 30 years |
| Interest-only | None |
For this example, assume the lender accepts the $36 million purchase price as the value for the LTV calculation and uses the NOI amounts shown. Actual lenders may apply different income and valuation methods.
A 70% LTV limit supports $25.20 million in debt. At 7.00% fixed interest and 30-year monthly amortization, annual debt service is approximately $2.012 million.
Same asset, different NOI and debt-sizing result
| Financing measure | Seller NOI | Buyer NOI |
|---|---|---|
| Underwritten NOI | $2.75M | $2.41M |
| DSCR on $25.20M loan | 1.37x | 1.20x |
| Meets 1.25x DSCR minimum? | Yes | No |
| DSCR-constrained maximum | $27.56M | $24.15M |
| 70% LTV-constrained maximum | $25.20M | $25.20M |
| Maximum under both tests | $25.20M | $24.15M |
Before the property-tax adjustment, LTV limits the loan. After the adjustment, DSCR becomes the more restrictive constraint.
The maximum supported loan declines by approximately $1.05 million.
This is a financing shortfall at closing, not another $1.05 million operating expense. It represents the difference in loan proceeds and therefore approximately the additional acquisition equity required, assuming the same purchase price and other funding needs.
A real lender may also impose debt yield, LTC, minimum reserves, valuation, or other requirements. The lender's NOI could differ from both the seller's and buyer's figures.
What happens to annual cash flow?
NOI is the property's operating income before debt service. For an unchanged loan and the same operations, a $340,000 increase in property taxes would also reduce annual cash flow after debt service by $340,000, before other below-NOI items.
But the original $25.20 million loan would fail the hypothetical 1.25x DSCR requirement under buyer NOI.
If the loan is reduced to approximately $24.15 million, annual debt service falls to approximately $1.928 million.
At that resized loan amount, the buyer's $2.41 million of NOI produces approximately $482,000 annually after scheduled debt service, before reserves, capital expenditures, sponsor fees, and other below-NOI cash requirements.
The lower debt service partly offsets the operating cash-flow pressure, but the smaller loan also requires additional equity at closing. Both effects belong in the investor-return model.
Step 5: Stress the property-tax assumption
Hold annual NOI before taxes at $3.23 million.
Recurring tax expense and indicated valuation sensitivity
| Scenario | Annual taxes | NOI | NOI reduction vs. seller | Value difference at 6% cap |
|---|---|---|---|---|
| Seller historical | $480K | $2.750M | — | — |
| Lower-tax case | $640K | $2.590M | $160K | $2.67M |
| Buyer base case | $820K | $2.410M | $340K | $5.67M |
| Higher-tax case | $1.00M | $2.230M | $520K | $8.67M |
These are illustrative scenarios, not assigned probabilities. The valuation column divides the annual NOI difference by 6.00%. It is not a DCF valuation, sale forecast, or levered equity-return calculation.
If the acquisition only meets our return target in the lower-tax scenario, the investment committee should understand that dependency.
Step 6: Model the timing, not just the amount
Suppose the buyer's first six months of ownership are modeled at the historical $480,000 annual tax run rate and the following six months at the $820,000 projected run rate.
A subsequent full year at the higher tax run rate produces $2.41 million of NOI, all else equal.
However, a lender may size the acquisition using the projected full-year tax obligation rather than a temporarily lower first-year expense. The lender's qualifying NOI may therefore differ from modeled Year-1 NOI.
This timing example does not describe the statutory assessment, accrual, or payment rules of any particular jurisdiction.
Do Not Confuse Property Taxes With Closing Prorations and Escrows
Property-tax underwriting also needs to reconcile with the closing statement and sources-and-uses schedule.
Depending on the transaction, the closing statement may include seller tax credits, prorations, unpaid prior-year taxes, supplemental assessments, appeal-related amounts, and lender-required tax escrows.
These items can affect cash required at closing, but they are not automatically adjustments to recurring property NOI.
A seller credit for taxes attributable to the seller's ownership period is not permanent operating income.
Likewise, a lender escrow deposit is generally a funding requirement, not an additional tax expense on top of taxes already included in NOI.
The model should distinguish annual expense, cash-payment timing, tax liabilities, and escrow funding without counting the same economic cost twice.
A one-time seller credit may fund a tax obligation. It does not eliminate the buyer's recurring tax expense.
The Purchase Price and Property-Tax Feedback Loop
A lower acquisition price may influence a buyer's future tax estimate in some jurisdictions. It does not automatically do so.
Suppose our buyer negotiates the same property from $36 million to $34 million.
A lower price improves the acquisition basis. But the tax estimate must still be supported by the applicable local valuation rules.
A countywide assessment may not change immediately, while a qualifying transaction in another jurisdiction may establish a new valuation basis.
Consider three illustrative scenarios using the same financing assumptions and $3.23 million of NOI before property taxes.
Repricing the same property under different forward-tax assumptions
| Measure | $36M acquisition | $34M, taxes unchanged | $34M, lower taxes |
|---|---|---|---|
| Purchase price | $36.00M | $34.00M | $34.00M |
| Assumed annual taxes | $820K | $820K | $780K |
| Underwritten NOI | $2.41M | $2.41M | $2.45M |
| 70% LTV loan limit | $25.20M | $23.80M | $23.80M |
| 1.25x DSCR loan limit | $24.15M | $24.15M | $24.55M |
| Binding loan limit | $24.15M | $23.80M | $23.80M |
| Purchase equity before costs and reserves | $11.85M | $10.20M | $10.20M |
The $780,000 tax estimate is a separate hypothetical scenario, not an automatic result of the lower offer. It requires its own supportable taxable valuation.
At $36 million, DSCR is the limiting loan constraint. At $34 million, LTV becomes the limiting constraint even if projected taxes decline.
A lower tax forecast can improve NOI and DSCR without increasing actual loan proceeds when another constraint is already binding.
The underwriting process must therefore recalculate purchase price, supportable tax expense, NOI, lender constraints, required equity, and investor returns together.
Purchase price, property taxes, and financing must be evaluated together. They should not be assumed to move proportionally.
What About Taxes on a Renovation Business Plan?
Value-add underwriting usually focuses on renovation costs and projected rent premiums. But we should also ask whether improvements may affect the property's future taxable value.
The answer depends on local law and the nature of the work. Routine repairs, replacement of existing components, major additions, and new construction may receive different treatment.
Not every renovation creates a separately taxable improvement.
A stabilized NOI forecast should reflect a supportable future tax expense, not simply higher rental revenue and the seller's original operating-cost structure.
This connects with our earlier analysis, Multifamily Renovation Premiums: When Does Value-Add CapEx Actually Create Value?
The principle is the same: additional investment should be measured against the incremental NOI it reasonably produces after related costs.
Can an Owner Appeal a Property-Tax Assessment?
Often, yes. Depending on the jurisdiction, an owner may be able to challenge assessed value, classification, taxability, or other determinations.
Supporting evidence might include comparable transactions, income-capitalization analysis, independent appraisals, property-condition documentation, or errors in assessor records.
But an appeal is not guaranteed savings, and filing deadlines vary.
Georgia, for example, generally allows an assessment appeal within 45 days of the date the annual assessment notice was mailed. That deadline should not be assumed to apply in other jurisdictions.
Nor should we automatically assume that an appeal suspends all tax-payment obligations. Applicable rules and potential refunds must be confirmed locally.
I would generally underwrite the defensible tax obligation and model potential appeal savings separately unless the reduction has been sufficiently established.
If the acquisition only meets its required return following a successful appeal, that dependency belongs in the investment thesis.
Seven Property-Tax Questions Before Submitting an LOI
- What has the property actually been assessed and billed? Obtain tax bills, valuation notices, parcel records, and supporting financial statements.
- Which tax rules apply? Verify classification, ratios, exemptions, limitations, millage, and special assessments.
- Will the transaction change the assessment? Evaluate qualifying transfers and the relevance of purchase consideration.
- When is the next valuation or reappraisal? Identify applicable dates and cash-payment timing.
- What is the supportable buyer tax forecast? Document the base estimate, source evidence, and reasonable sensitivity cases.
- What happens to financing and required equity? Recalculate NOI, DSCR, other loan constraints, liquidity needs, and projected returns.
- Are there pending appeals or outstanding liabilities? Verify deadlines, tax prorations, and whether specialist advice is necessary.
If these questions cannot reasonably be answered, the tax forecast is not yet adequately supported for a final acquisition decision.
Common Property-Tax Underwriting Mistakes
- Using a generic 3% annual growth assumption. A flat increase can miss a scheduled reappraisal, change in ownership treatment, or limitation reset.
- Assuming the purchase price automatically becomes assessed value. This is not a universal property-tax rule.
- Applying homeowner protections to investment property. Homestead-specific benefits may not apply to larger apartment communities.
- Treating assessed-value growth as identical tax-bill growth. Tax rates, levies, and applicable adjustments matter.
- Counting appeal savings before they are supported. A possible reduction is not dependable base-case NOI.
- Double counting property taxes. An expense already reflected in NOI should not be deducted a second time from capitalized value.
- Confusing closing cash movements with recurring expenses. Seller credits and escrows need separate treatment.
- Ignoring the next buyer's tax position. Exit valuation and future financing may depend on the taxes recognized by the next owner.
These are not minor modeling details. They can change the acquisition price and the quality of the projected return.
How Property Taxes Fit Into Institutional Acquisition Decisions
In our recent article, What Institutional Multifamily Buyers Look for in 2026: The Real Buy Box Behind the Deal , we examined mandate, market, basis, income, capital, execution, portfolio fit, and exit.
Property taxes influence several of those decisions simultaneously.
They affect the income being purchased, the value supported by that income, financing proceeds, required equity, and potentially the valuation available from a future buyer.
Our hypothetical 240-unit example shows a $340,000 annual reduction in NOI and approximately $1.05 million of reduced loan proceeds under the specified financing tests.
The buyer could negotiate a lower price, reduce leverage, contribute additional equity, investigate a valid appeal, or pass on the deal.
The appropriate response depends on the strength of the evidence and the full investment economics.
After using a reasonable forward tax obligation, does the acquisition still meet our investment criteria at the negotiated price?
Final Takeaway
Property-tax reassessment is not merely an accounting adjustment.
It can change the acquisition basis we can defend, the amount of debt available, the equity investors must contribute, and the returns those investors may receive.
The seller's historical taxes tell us something important about the property's past. Our underwriting must establish what ownership is reasonably expected to cost us.
That requires understanding the local rules, reviewing the parcel's records, forecasting the appropriate timing, and measuring the economic consequences before committing capital.
The objective is not perfect prediction. It is knowing which assumptions are supported, which remain uncertain, and how much that uncertainty should affect the acquisition decision.
For me, the standard is straightforward.
If we cannot defend the property-tax forecast, we cannot fully defend the NOI. And if we cannot defend the NOI, we should question the price we are willing to pay.
Frequently Asked Questions
Do multifamily property taxes always increase after a sale?
No. The outcome depends on the jurisdiction's valuation rules, ownership-change provisions, tax rates, exemptions, and property circumstances.
Does purchase price automatically become assessed value?
Not universally. A qualifying sale may establish a new assessment basis in some jurisdictions or provide evidence relevant to future valuation. Others follow scheduled reappraisals.
How does a tax increase affect NOI?
Higher recurring property taxes generally reduce NOI dollar for dollar when all other factors remain constant and no recovery applies.
How do taxes affect multifamily loan proceeds?
Higher taxes can lower NOI and DSCR. Loan proceeds may decline if DSCR becomes the binding lending constraint. LTV, debt yield, valuation, and other restrictions also matter.
Can a lower purchase price reduce property taxes?
Potentially, depending on the jurisdiction's assessment rules and the relevance of purchase consideration. It is not guaranteed.
Can renovations affect assessed value?
Yes. Treatment depends on local law and the nature of the improvements. Routine repairs and significant new improvements may differ.
Are property-tax escrows another operating expense?
Generally, no. Escrow deposits are cash held to pay taxes. They should be tracked without counting the underlying tax expense twice.
Can apartment owners appeal assessments?
Often yes, subject to local eligibility, deadlines, evidence, and procedures. Success is not guaranteed.
Should buyers use the seller's T12 taxes?
Use them as historical evidence, then independently forecast the buyer's forward tax obligation.
How far forward should property taxes be modeled?
Through the full planned hold, including reasonably foreseeable changes in assessments, rates, valuation schedules, improvements, and acquisition or disposition timing.
Model the Tax Expense Before Committing the Capital
MSA Analyzer supports multifamily operating-expense underwriting, NOI analysis, debt sizing, scenario comparison, and projected investment returns.
Use it to examine how revised property-tax assumptions affect acquisition economics, while grounding those assumptions in assessor records, local tax rules, and property-specific evidence.
Explore MSA Analyzer →Sources & Data Notes
Government statutes and published guidance reviewed October 27, 2026. All acquisition amounts, assessed values, tax estimates, lender terms, loan proceeds, and calculations in the worked example are illustrative. They do not represent an actual XSITE Capital investment, an official tax assessment, a lender quotation, legal advice, or tax advice. Property-specific treatment should be confirmed with the appropriate taxing authority or adviser.
- Georgia Department of Revenue: Property Tax Valuation
- Georgia Department of Revenue: Property Tax Millage Rates
- Georgia Department of Revenue: Property Tax FAQs and Appeals
- North Carolina General Statute 105-286: General Reappraisal
- South Carolina Code: Sections 12-37-3135 and 12-37-3140
- Ohio Department of Taxation: Reappraisal and Update Schedule
- Ohio Department of Taxation: January 2026 Schedule Update
- California Board of Equalization: Change in Ownership
- California Board of Equalization: Supplemental Assessments
- Florida Statutes (2026): Section 193.1555
- Texas Comptroller: Property Valuation and Circuit-Breaker Limitation
More from the Digest
Keep exploring expert takes on multifamily underwriting and market intelligence.
What Institutional Multifamily Buyers Look for in 2026: The Real Buy Box Behind the Deal
What do institutional multifamily buyers look for in 2026? Learn the eight-part buy box, market data, financing tests, and a worked 300-unit acquisition example.
How We’d Build a 1,000-Unit Multifamily Portfolio Today: Lessons From XSITE Capital
What serving as XSITE Capital's primary underwriter and underwriting every XSITE deal has taught me about acquisition discipline, market selection, debt, liquidity, operating scale, and why unit count should never be the goal.
What Is a T12? How Institutional Buyers Read a Trailing 12-Month Statement
A T12 is one of the most important documents in multifamily underwriting—but most investors read it too casually. This guide breaks down how to analyze a T12 properly, pressure-test the numbers, identify red flags, and adjust historical performance into forward reality.